
1031 Exchange Basics
Understanding The Process
“A known tax deferral strategy”
A 1031 exchange can be a valuable tax-deferral strategy, but it only works when the property, structure, and timing all line up. This page explains the basics in plain English so you can understand what qualifies, what deadlines matter, and what to review before closing. Section 1031 applies only to certain exchanges of real property held for business or investment use, not property held primarily for sale. (IRS)
A 1031 exchange is a process that may allow an investor to defer gain when exchanging qualifying real property for other qualifying real property of like kind. In practical terms, that usually means selling investment or business real estate and acquiring replacement real estate through a compliant exchange structure rather than treating the transaction as a taxable sale followed by a separate purchase. (IRS) The rules are narrower than many people expect. For 2018 and later years, Section 1031 applies only to real property held for use in a trade or business or for investment. It does not apply to real property held primarily for sale. For instance, equipment, cars, art, boats, Section 1031 (IRS)
**Investors are always advised to consult with the CPA, Attorney, and qualified intermediary to review all the facts and details of each specific exchange.
What is a 1031 Exchange?
Why do a 1031 Exchange?
“The Why?”
-
✓ Tax deferral
✓ Diversification
✓ Tax-advantaged cash flows
✓ Wealth preservation
-
By exchanging the property for like-kind real estate, property owners may defer Their tax and use all the proceeds for the purchase of a replacement property.
-
✓ Relieve the management burden of active real estate
✓ Diversify your real estate holdings both by geography or property type
✓ Invest in a single asset or multiple properties
✓ Aids and assists in estate planning
✓ Own or share in institutional grade real estate holdings
What is “like kind”?
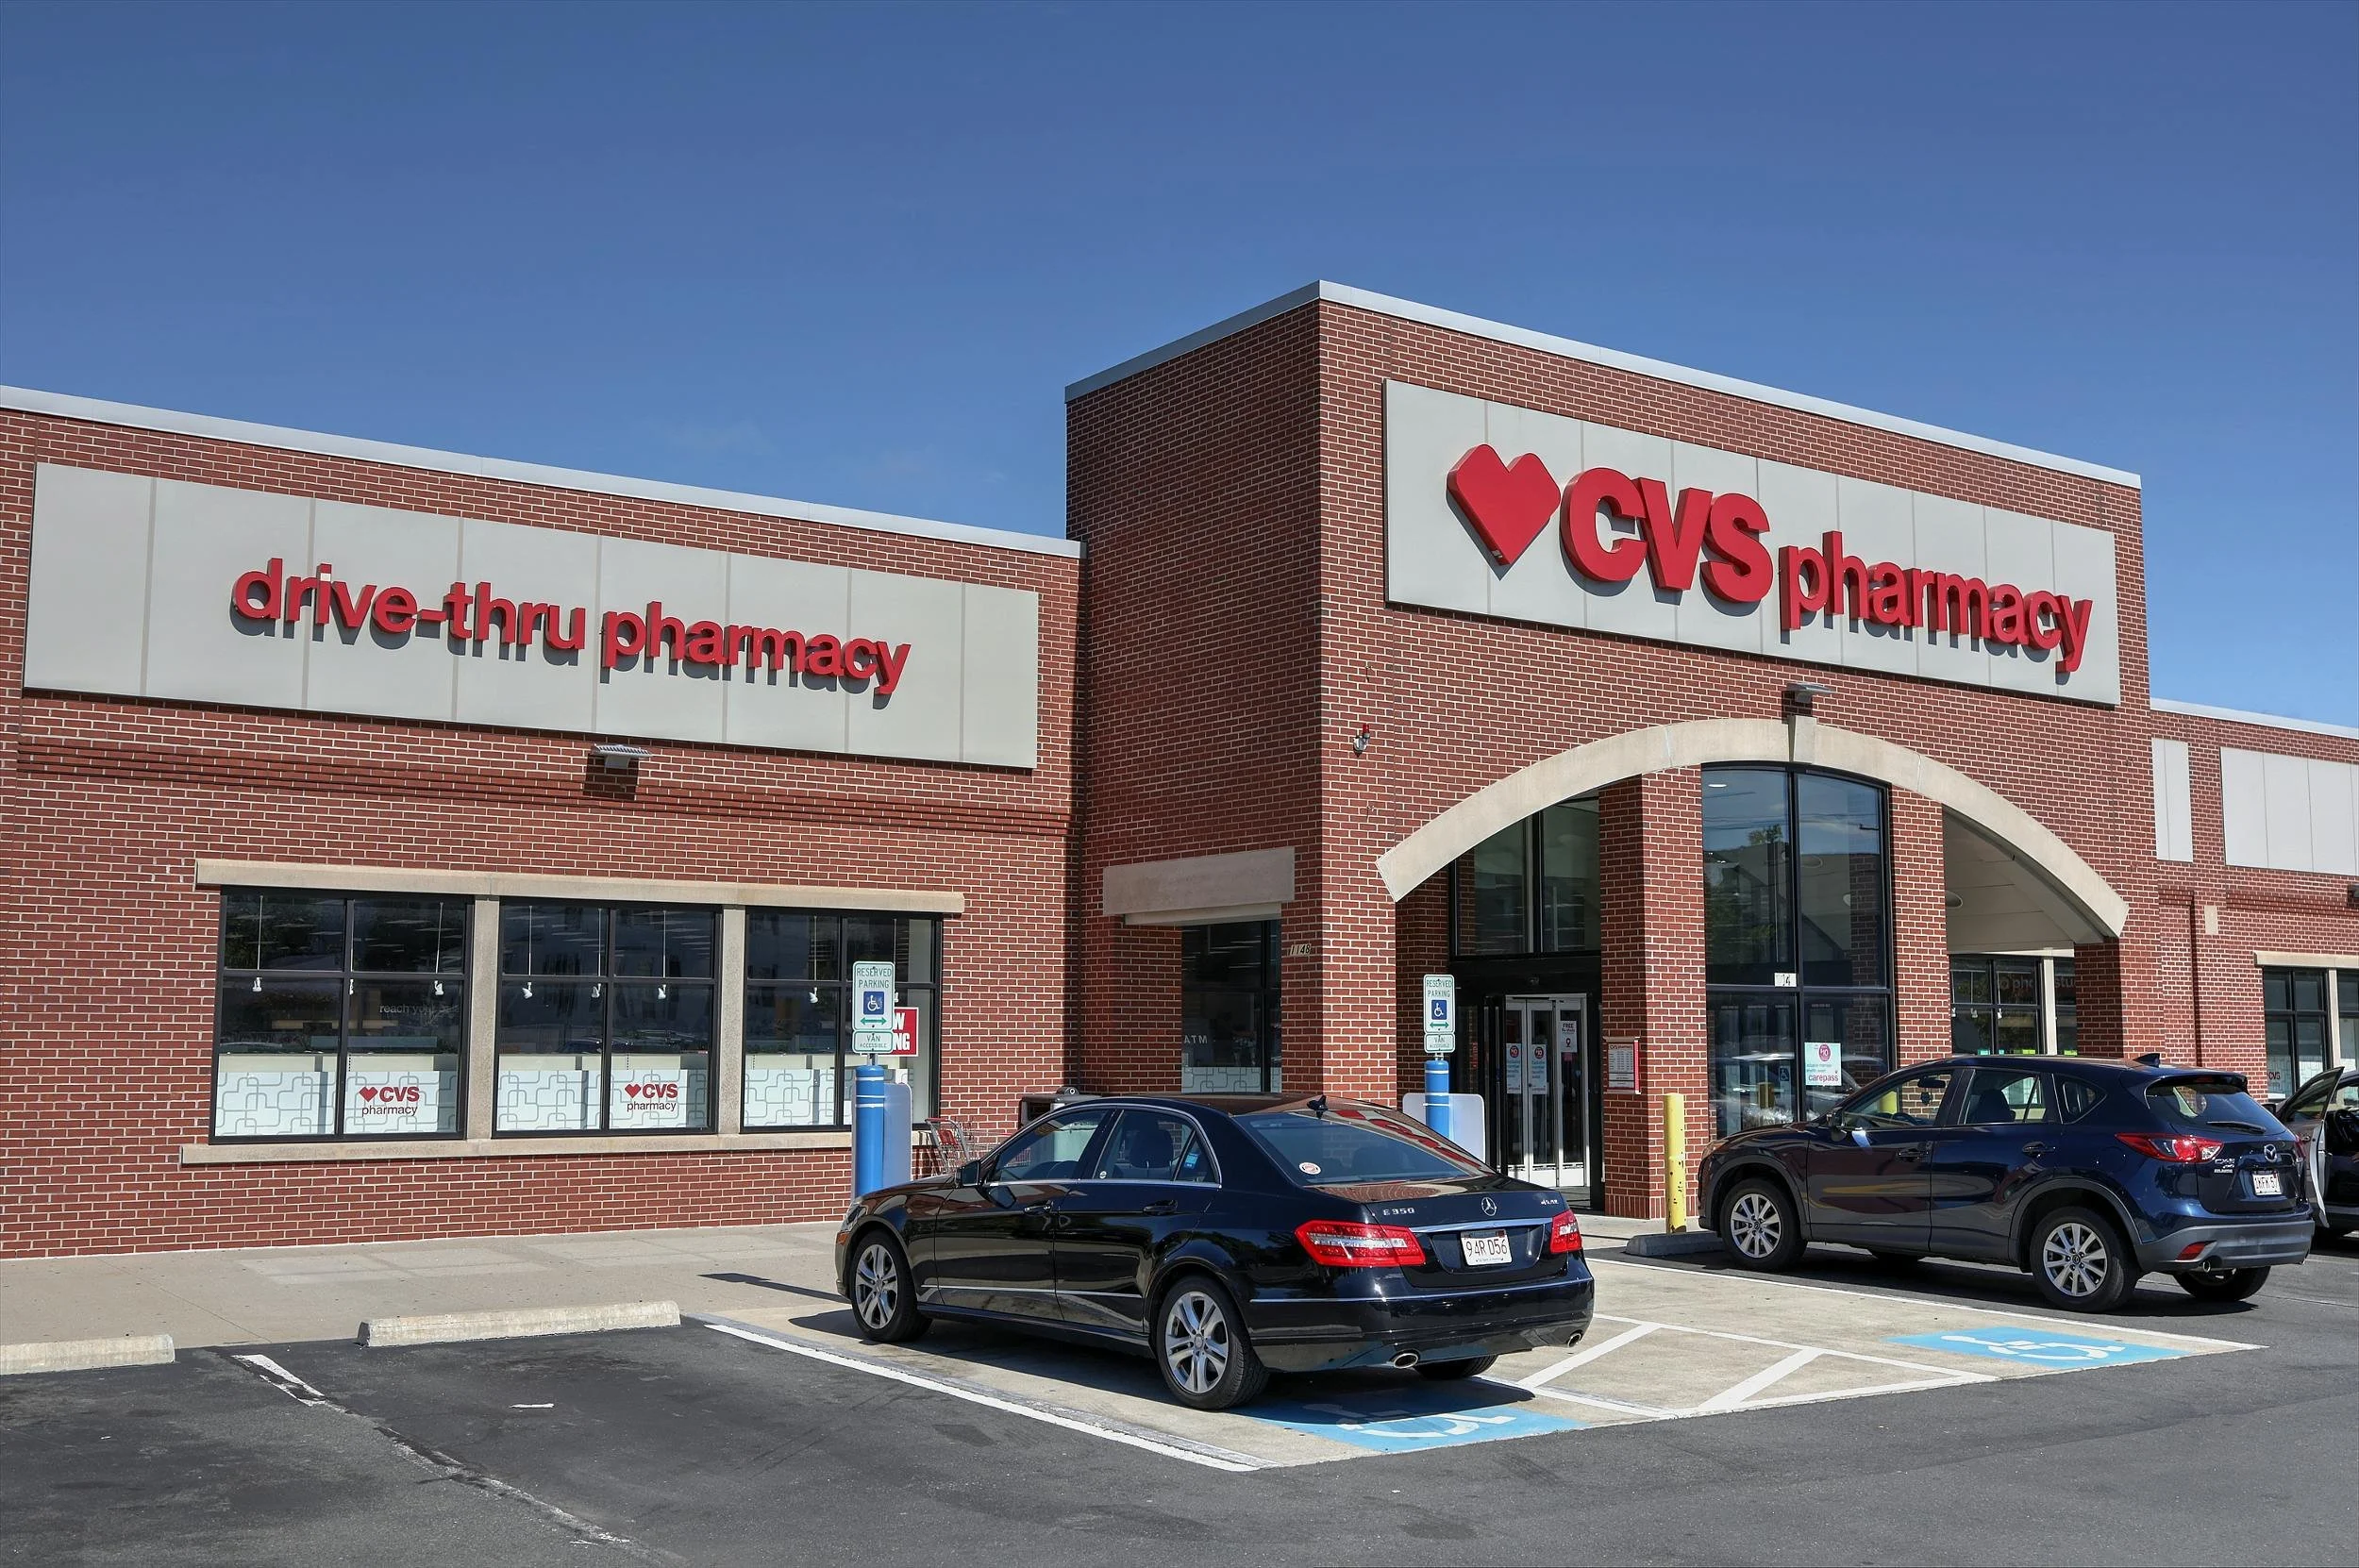
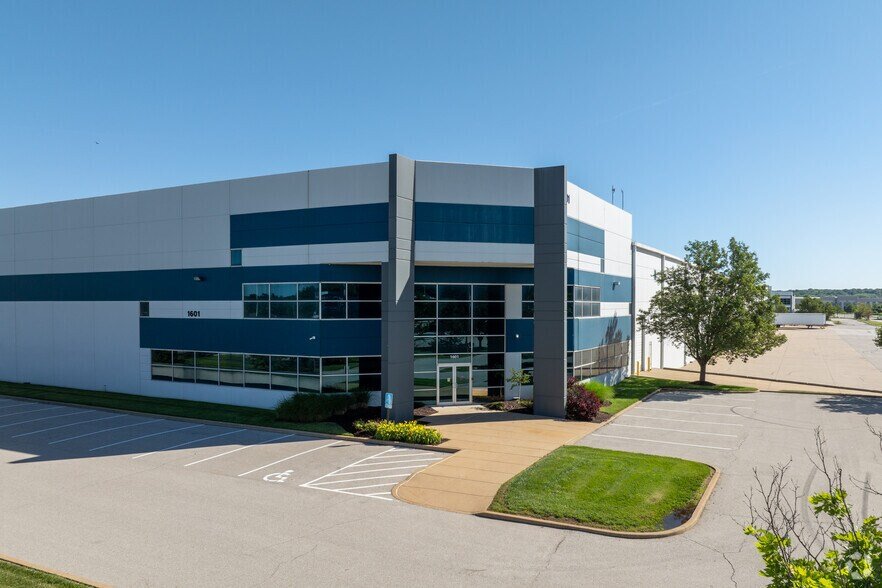
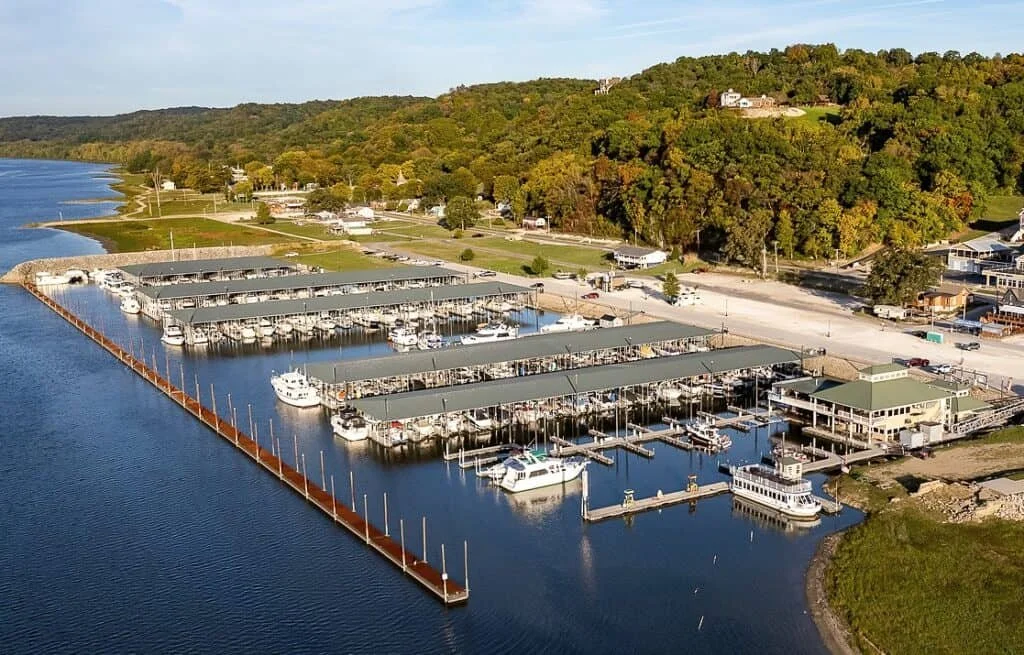
LIKE-KIND PROPERTIES MAY INCLUDE:
Multi-family apartment buildings
Single family rentals
Condominiums -duplexes (rentals)
Office buildings
Retail centers
Warehouses – storage
Hotels
Vacant lots, Land
Water, Air, and Mineral Rights
Development Rights
Easements
Tenant In common Interests(TIC)
Delaware Statutory Trust (DSTs)
Motels Interests
Examples of like-kind exchanges.
What may also qualify?
Some interests in real property can qualify even when they do not look like a standard fee-simple purchase. For example, the IRS says a real estate lease with 30 years or more remaining may qualify as like-kind real property in the right context. Certain dwelling units may also qualify when they meet investment or business-use requirements rather than personal-use treatment. (IRS)
A properly structured Delaware Statutory Trust, or DST, can also be relevant. In Revenue Ruling 2004-86, the IRS concluded that a taxpayer may exchange real property for an interest in the Delaware statutory trust described in that ruling without recognition of gain or loss under Section 1031, if the other requirements of Section 1031 are satisfied. (IRS)
→
→
Investment property to investment property
A rental property may be exchanged for another rental property, commercial building, or land, as long as both properties are held for investment or business use. (IRS)
One replacement or multiple replacements
A replacement strategy may involve one property or more than one property, provided the identification rules are followed correctly. (IRS)
→
→
Improved property to unimproved property
Improved property can be like kind to unimproved property. The IRS gives examples such as city property exchanged for farm property, or improved property exchanged for unimproved property. Section 1031 -(IRS)
Foreign property note
Real property in the United States is not like kind to real property located outside the United States. Section 1031 (IRS)
What usually does NOT qualify
Personal residences generally do not qualify. Real property held primarily for sale generally does not qualify. Personal property and intangible property that are not treated as interests in real property also generally do not qualify under current Section 1031 rules. (IRS)
The Timeline that Drives the Exchange
A delayed exchange runs on a fixed clock. Replacement property must be identified within 45 days after the transfer of the property you give up, and it must generally be received by the earlier of 180 days after that transfer or the due date of your tax return, including extensions, for the year of the transfer.
The Rules & Timing of a 1031 Exchange
DAY 1
Sell your property; proceeds are escrowed with a Qualified Intermediary (QI).
To successfully complete a 1031 Exchange and defer your capital gains liability, you must follow very specific requirements over a strict 180-day timeline.
DAY 45
Identify a property within 45 days.
DAY 180
Close on your new property within 180 days of the sale of the relinquished property
In addition to the timing considerations, a qualifying exchange requires you to:
Purchase a replacement property of equal or greater value
Reinvest all equity
Obtain an equal or greater amount of debt on the replacement property
Failure to satisfy these requirements will create a tax liability.
How Identification Rules Work
Three-Property Rule
You may identify up to three replacement properties, regardless of fair market value. (IRS)
The IRS places limits on the number of replacements and additional valuation guidelines for your identification process you can identify. Section 1031 (IRS)
200 Percent Rule
You may identify any number of properties as long as their total fair market value does not exceed 200 percent of the fair market value of the property you gave up. (IRS)
This is one reason investors do better when they build the shortlist early. The rules are manageable, but they leave less room for improvising late in the process.
95 Percent Exception
If you identify more than the limits above, identified property is still counted only in the narrower circumstance where the property you actually receive is at least 95 percent of the total fair market value of all identified replacement properties. (IRS)
P R E P A R A T I O N I S K E Y
“By failing to prepare, you are preparing to fail”
- Benjamin Franklin
Preparation is Key
Why?
A smoother exchange usually starts before the closing table. The exchange cannot involve actual or constructive receipt of the sale proceeds, which is why the qualified intermediary and the exchange structure matter early, not after the fact. (IRS)
Five things to review before the sale closes
Choose your qualified intermediary early
The exchange structure should be set before closing so proceeds are handled correctly. (IRS) ✓
Model the tax exposure with your CPA
Before you decide what to defer, you should know what gain, basis issues, and potential recognition you are actually dealing with. ✓
Decide what your replacement path looks like
One direct property, multiple properties, fractional structures, or a mix of options can lead to very different timelines and review needs.✓
Build the shortlist before the 45-day window gets tight
A rushed shortlist usually creates weaker decisions. ✓
Work backward from Day 45 and Day 180
Your broker, CPA, lender, attorney, and qualified intermediary all need the same timeline. ✓
What tax deferral really means
When qualifying real property is exchanged solely for like-kind real property, gain is generally not recognized at that point. But if money or non-like-kind property is received as part of the exchange, gain is generally recognized up to the value of what was received. (IRS)
That is why a real exchange review is not just about finding another property. It is also about understanding proceeds, basis, closing items, and whether any part of the transaction creates current recognition. Form 8824 is used to report the exchange and calculate deferred gain. (IRS)
It’s never too early to plan or prepare.
Whether you are months from a sale or already watching the clock, an early conversation can help you understand the following :